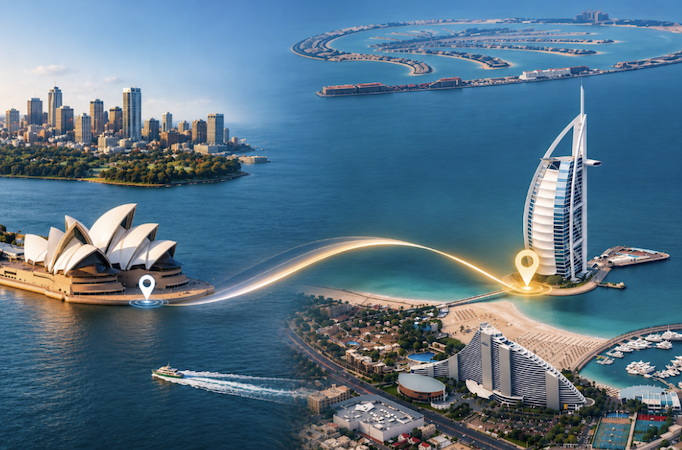
For a growing number of Australian entrepreneurs, Dubai is no longer just a stopover on the way to Europe. It has emerged as a serious global business hub, attracting founders across technology, fintech, e-commerce, international trading, financial services and digital enterprises.
With streamlined company formation, access to international markets, business-linked residency options and a competitive corporate tax regime, Dubai offers compelling advantages over operating solely from Australia.
However, many founders overlook a critical distinction: establishing a company in Dubai does not automatically end their tax obligations in Australia. A UAE trade licence, residency visa, or even a functioning business overseas does not necessarily remove the Australian Taxation Office (ATO) from the equation. Founders who confuse company formation with a change in tax residency may discover the consequences at the worst possible time: during an ATO audit.
"A Dubai licence alone doesn't stop the tax bill at home. The exit has to be planned as carefully as the arrival," says Shayan Nasiri, Co-Founder of GenZone, a Dubai-based firm that handles company setup in Dubai for founders from over 50 countries.
Tax residency depends on more than a visa
The ATO assesses individual tax residency using four tests: the resides test, domicile test, 183-day test and the Commonwealth superannuation test. Meeting any one of these can result in remaining an Australian tax resident, potentially subject to Australian tax on worldwide income.
Consider a founder who establishes a technology company in Dubai while their spouse, children and family home remain in Sydney. Despite holding a UAE residence visa and Emirates ID, their Australian tax residency may remain intact.
The ATO examines where life is genuinely centred, including family connections, accommodation, financial arrangements and the permanence of the move. Passport stamps alone rarely tell the full story.
Leaving Australia can trigger capital gains tax
One of the most overlooked consequences of relocating is Australia's exit capital gains tax treatment.
When an individual ceases Australian tax residency, most CGT assets that are not taxable Australian property are treated as though they were sold at market value immediately before departure. This can include shares, private business interests and cryptocurrency holdings.
Australian real estate and certain other taxable Australian property are generally excluded.
Eligible individuals can elect to disregard the deemed gains and losses, but doing so generally keeps the affected assets within Australia's CGT system until a later disposal or other relevant event.
For founders holding substantial investment portfolios or appreciated digital assets, a move to Dubai can create tax consequences before their new business earns its first dirham.
A Dubai company can still be Australian for tax purposes
Registering a company in the UAE does not automatically remove it from Australia's corporate tax system.
A foreign-incorporated company can be considered an Australian tax resident if it carries on business in Australia and its central management and control are located there, or it satisfies the applicable voting-power condition.
Under Taxation Ruling TR 2018/5, the ATO examines where high-level business decisions are genuinely made, rather than simply where incorporation documents were issued.
If a founder continues directing major strategic decisions from Melbourne, a Dubai trade licence and corporate bank account may not deliver the intended tax outcome.
Low tax does not mean no tax
The UAE generally applies 0% corporate tax on taxable income up to AED 375,000 and 9% above that threshold.
Qualifying Free Zone Persons may receive a 0% rate on qualifying income, provided they meet conditions involving business activities, adequate substance, audited financial statements and other compliance requirements.
Companies subject to the UAE corporate tax regime generally must register and file returns, even when no tax is payable. This makes UAE tax and accounting compliance an ongoing responsibility.
Australia and the UAE also lack a comprehensive double taxation agreement. Their Comprehensive Economic Partnership Agreement, effective from 1 October 2025, facilitates trade and investment but does not provide income tax residency tie-breaker rules.
Consequently, founders must carefully document their relocation and assess their obligations under both countries' domestic tax laws.
Plan the exit before the arrival
A successful relocation begins with understanding Australian tax residency, exit CGT exposure and corporate management arrangements before establishing a UAE company.
Founders should first consult an Australian tax adviser, then structure their Dubai business around their commercial activities and residency requirements.
The UAE process typically involves obtaining a trade licence, residence visa, Emirates ID, corporate bank account and completing tax registration. Eligible investors may also explore the ten-year Golden Visa, including property investment pathways starting at AED 2 million.
Founded in 2022 by Kevin McKenzie and Shayan Nasiri, GenZone helps international entrepreneurs establish businesses and relocate to Dubai. McKenzie, a former Canada Revenue Agency professional, brings experience in tax administration.
The firm also connects clients with independent advisers in their home countries, including Australia, without receiving referral commissions, keeping departure-related tax advice separate from UAE company formation.
The bottom line
Dubai offers significant advantages for Australian entrepreneurs who genuinely relocate their lives and business decision-making. However, a UAE company cannot substitute for a properly planned departure.
The most effective relocation strategy begins with getting the Australian exit right, not simply obtaining a Dubai trade licence.